“It can be concluded that both shale oil and shale gas are unlikely to be economically viable in this current low hydrocarbon price environment and even if there is a return to recent higher prices; it is likely that the industry would require significant subsidy or significant efficiency progression before it could be used at any kind of scale.”
“Even if the extraction can be proven to be environmentally ‘safe’ the experience of the United States shows that it risks bringing boom-and-bust to our communities as waves of temporary jobs move rapidly through without rooting themselves in local economies.”
My first paper written for the Common Weal has been published today. The Economics of Shale Gas Extraction is the first major paper to be published in Scotland focusing on the economic, rather than environmental, impacts of the industry particularly on the local communities which will be hosting the wells.
Key Findings:-
The SGE market in the US and, so far, in the UK is dominated by larger companies occupying the most profitable licences. There is little scope for community owned or small company development to occupy a significant market share.
Individual wells become largely non-productive within a few years of development which, due to market demand for constant production, forces companies to continue drilling new wells in new locations at a rapid pace.
The low recoverable volumes and high capital and running costs of wells may render profit margins comparatively small and extremely sensitive to oil and gas pricing. There appears to be little scope for economic development of SGE in the UK until and unless wholesale prices return to historic highs and even then significant subsidy may be required.
Communities are likely to be significantly adversely impacted by nearby SGE fields. The concentrated pattern of land ownership and comparatively weak situation of local government renders communities vulnerable to being unable to capture wealth generated by nearby wells whereas the burden of environmental degradation or even simply the threat of such degradation can lead to community stress and negative economic effects.
The jobs created by SGE appear to be short-lived and highly mobile. The job demographic of the planning, drilling and production phases are each relatively exclusive meaning that they will move to the next site more rapidly than the wells themselves do. This creates the risk of a “Boom-Bust” effect in communities.
Shale oil and gas is considered a relatively poor source of fuel due to high extraction costs. The UK’s reserves are also likely to have an insignificant impact on global markets and hence a negligible impact on end-user prices.
Significant externalities have been identified in the form of environmental degradation due to methane leaks. The costs to mitigate these may exceed the lifetime revenues generated by the well which produced them. Further, the UK has a poor record in terms of ensuring adequate decommissioning and restoration bonds which may lead to further public funding being required after the SGE companies have left an area.
Whilst much of the attention on the shale oil/gas and fracking industry has been focused on the environmental impact, less attention has been paid to the economic effects. Even if the extraction can be proven to be environmentally “safe” the experience of the United States shows that it risks bringing boom-and-bust to our communities as waves of temporary jobs move rapidly through without rooting themselves in local economies. Scotland’s history of concentrated land ownership and comparatively poor local government also risks creating a vast transfer of wealth benefiting the already wealthy whilst potentially leaving communities to foot the bill for cleaning up. All for a fuel which the government has been told will not even benefit us in the form of lower energy bills.
There should be no place for fracking in Scotland or the UK.
“I would say is that every public-private partnership in Scotland has delivered new hospitals or new schools in Scotland on time and within budget and that’s the sort of success I want to see in every building.” – Jack McConnell, 2002
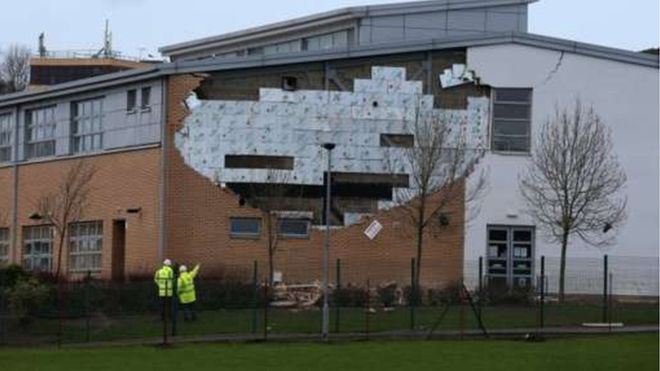
Oxgangs Primary School, 2016. Built by PFI in 2005
The dramatic news from Edinburgh in the past couple of weeks has put into sharp focus the failures of some of the finance models used by our regional councils to build schools, hospitals and other public buildings in recent years. Public/Private Partnerships (PPP), Private Finance Initiatives (PFI) and, less well known, Lender Option, Buyer Option (LOBO) Loans have burdened our councils with near-crippling financial obligations and, as we now know, have too often failed to deliver on even the basic standards of results required. Just what these deals are and why they have been used is a topic which requires a bit of discussion.
PPP/PFI
Public Private Partnerships, of which Private Finance Initiatives are a specific type, are a form of capital investment introduced to the UK in the early 1990’s by Major’s Conservative government as an alternative to tradition procurement methods of the time. In traditional public investment models a local authority might decide to build an asset such as a school itself in a purely publicly funded model or it might contract a private source to build the school and then take over the full running costs of the project afterwards. The Tories were driven by an ideological pledge to reduce the budget deficit (then known by the catchy title of “public sector borrowing requirement“) and identified the use of PFI as a means to do this.
Instead of paying for a project out of the capital budget either up-front or over the span of the construction phase, PFI would spread the costs over a medium or long term contract, often more than 20 years. This reduced the single year outlay and hence massaged the budget figures.
It was under the Labour government though that PFI really took off as it had the advantage of taking capital debts “off-book” and allowed Gordon Brown to simply stop counting them towards the deficit entirely. This gave the illusion of the fiscal prudence on which he banked much of his reputation. This was doubled down in Scotland by Jack McConnell’s Labour/Lib Dem government which led to Scotland, with 8.5% of the UK population, ending up with some 40% of the UK’s PFI funded schools.
The lie to the illusion can be found in the realisation that the private sector doesn’t work for free. These contracts almost certainly mean that the total cost to the council over the lifetime of the council is significantly larger than the up-front capital costs.
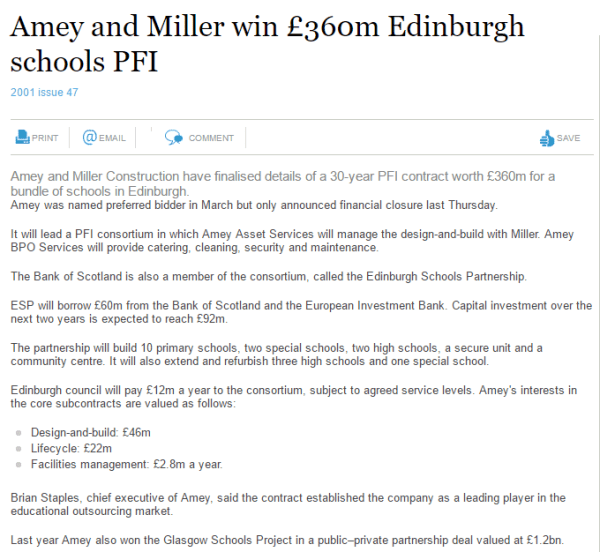
To take a recent example concerning some of the schools in Edinburgh, the private company involved will be paid £12 million per year for 30 years for a project valued at £68 million in up-front costs and an additional £84 million in management costs. Subtracting the running costs, this represents an annualised return on capital investment for the company of 10% per year. For contrast, David Cameron’s offshore tax haven shares “only” earned him about 6.75% per year.
And this doesn’t even represent the worst example of increased costs due to PFI. Contracts worth three or four times the capital investment are common. Some have been found to be worth a staggering ten or even twelve times the total outlay.
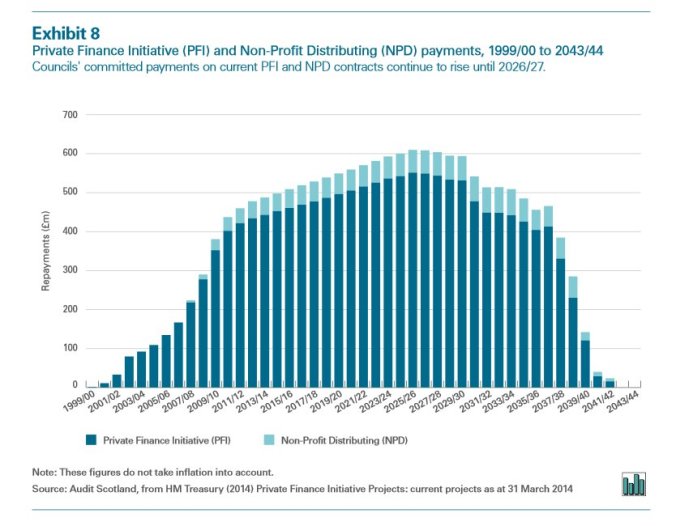
It is these ongoing payments which are particularly affecting our own regional councils and the problem is only going to get worse with the peak of the outgoing payments not expected to hit till the mid 2020’s.
Whilst one of the advantages of PPP’s often touted is the obligation for the private company to maintain the asset over the lifetime of the contract this can be a double-edged sword. One of the other “advantages”, mentioned in the UN ESCAP video above, is the “realisation of private sector efficiency savings”. That can mean “cutting-corners” to you and me. If the company is required to maintain a school for only 30 years but is then free from that obligation on year 31 then the inducement to build to the minimum possible standards to see out that contract is strong. Indeed, there is some anecdotal eyewitness evidence that exactly this has taken place. Schools which, by today’s standards are insufficient but which nonetheless stood for more than 100 years are being replaced with buildings designed to last less than a quarter of that and, has been seen, sometimes don’t even make it that far. This is not “long term planning”. It is certainly not helped by the generally low standards of our building regulations. A private company will rarely build at anything other than barely above the minimum legal standards so if we’re going to continue involving “the market” in our infrastructure projects then we’re going to need to have a discussion about increasing those standards to something more suitable for the 21st century. Whilst PFI specifically may have been abandoned in Scotland, this discussion over standards remains.
LOBO Loans
Lender Option, Buyer Option loans make up a far smaller proportion of council borrowing than PPP/PFI and have hit fewer headlines but they are still a symptom of the chronic dysfunction of our public borrowing system.
These loans were launched in 2000 as an alternative to the National Loans Fund which, whilst cheap and stable due to being funded by UK gilts, are sometimes quite limited in scope and therefore not always avaliable when required. Instead, the public body can approach a commercial bank for a long term, often more than 40 years, loan which is offered at an initially low “teaser rate” but which includes a clause which allows the lender to change the interest rate, usually upwards, are regular, often annual, intervals.
Sometimes these rate adjustments carry with them a contract exit clause but one can imagine the conversation in that case.
Bank: “So, we’re planning on increasing your interest rate from 2% to 5%. Under Section 4 of our contract, you can exit the loan by paying back the outstanding primary plus our exit fee.” Council: “If we had that kind of money, we wouldn’t have needed the loan.” Bank: “Ok. 5% it is. See you next year!”
These loans were often offered to and accepted by councils without the council quite appreciating the potential volatility and uncertainty that these changes would represent, which is quite understandable as these contracts have been criticised as being some of the most complex in the financial world and as our locally elected representatives aren’t necessarily chartered accountants it’s perhaps understandable that some would have simply been sucked in by those teaser rates which, at the time, undercut even those bonds offered by the NLF.
What Next?
I’m not going to pretend I have a magic solution to all of this. Some have discussed simply canceling and renationalising PFI funded assets but whilst I have some sympathy for this I have concerns also. Right now, we simply don’t know how far the record of substandard workmanship within the works built runs and, in fairness to the companies behind this disaster, they are upholding their obligation to pay the costs of repair and, if required, rebuild of these schools. If the contracts were canceled before we know the extend of the repair bill then we might simply be bailing out a huge debt. I can see some kind of scope for some kind of renegotiation over the annual payments or contract terms, perhaps with some kind of profit cap. Perhaps the companies could be offered an exit but made to put up a bond in case future issues arise although as we’ve seen from the coal and, more recently, the steel industry those bonds themselves need to be planned carefully lest they prove insufficient or evadable.
In future, a more sustainable method of public borrowing and investment needs to be examined. The Common Weal has a proposal to use a mutual limited company to leverage funds backed by Scottish issued bonds to invest in our public infrastructure which is perhaps one of the better ways to go about this issue although it is acknowledged that Scotland’s very limited borrowing powers even under the “new powers” of the Scotland Act 2015 will likely cap the viability of such a scheme. Obviously, an independent Scotland wouldn’t have that problem but until that’s sorted, we may need to think of something else.
Economics: The art of explaining why all of your models fail to predict either the future or the past.
Click image above for data
It’s that time of year again when everyone starts looking at the first page of a dense booklet of economic data and uses it to wildly forecast despite long known limitations in doing so. So it’s also, once again, time for me to try looking a little further to tease out some details that others might have missed.
First, to get some of the headline figures out of the way. There has been a slump in offshore oil revenue due, largely, to the crash in the oil price resulting from the ongoing economic conflict going on between Saudi Arabia and the US.
This has caused oil revenues to drop from £4.0bn in 2013-14 to £1.8bn in these current figures. And thus came sic a cry of a “>£2 billion BLACK HOLE” from certain sources…
…except…total current revenue is only down £600 million. Down from £54.050 billion last year to £53.443 billion this year. That’s just a touch over 1% of a change and is comparable to some of previous year’s “budget underspends“, thus it could even be said to be within the margin of error of budget estimates. So what is going on?
The European Court of Justice has released its judgment of the Scottish Government’s proposals to introduce a minimum unit price on alcohol.
Their judgment, published here, states that the proposals as written would be illegal on the grounds of being discriminatory towards cheap alcohol imports and thus would be a restriction on the free movement of goods within the EU.
They have, however, upheld the Scottish Governments arguments that MUP would lead to substantial health and social benefits and have agreed that it would, indeed, meet the goals of both reducing hazardous alcohol consumption and alcohol consumption in general (in an earlier article I noted that Scottish consumption of alcohol can be seen as substantially higher than the UK average simply by examining the tax records).
The court has therefore not banned MUP completely but has ruled that it cannot be implemented until and unless the national courts (i.e. Edinburgh and then the inevitable appeal to the Supreme Court in London) rule that the same alcohol reductions cannot be achieved via taxation. This sets out a test to be met by the Scottish Government.
But if that test is failed and taxation ruled appropriate, what form could it take?
The obvious first step would be alcohol duty but this is currently a reserved power and its devolution was ruled out of the Smith Agreement and the subsequent Scotland Act 2015 Bill. I would think it unlikely, given the current track record, that an amendment to devolve alcohol duty would succeed at this point so I think I’m safe in assuming that it will remain in Westminster hands. Nor, do I suspect, will George Osborne be keen to adjust his own plans for the UK simply to allow the Nationalists even a moment of victory so I can’t see him being amenable to changing alcohol duty at UK level either.
There is another way though, as pointed out by Andy Wightman on Twitter today, the Scottish Government currently DOES have the power to create new LOCAL taxes. If the courts ultimately agree with the ECJ that taxation would be just an effective method of reducing alcohol consumption as MUP then this would be a method within the competence of the Scottish Government to implement without further devolution or delay.
Such a tax need not be set locally, national legislation could fix the rate, though the advantages to doing so are quite strong. By keeping money within areas particularly blighted by alcoholism and alcohol abuse and by allowing the rates to be set to particularly target these areas the greatest good could be done the fastest. Conversely, those areas which perhaps see a lot of through traffic, people traveling into town for a responsible night out say, but suffer little actual harm from chronic abuse may wish to set rates somewhat lower so as to avoid driving away too much business.
While we’re looking at locally devolved alcohol sales taxes we could also take the advantage of the discussion to bring back proposals for alcohol production taxes too. Scotland is perhaps best known for its whisky exports but what is lesser known is the fact that many of the most famous distilleries actually employ comparatively few people and yet produce vast sums of money for their generally multinational corporate owners without doing all that much for a local area which often gives their very name to that drink. Given that these distilleries, and many brewers and other manufacturers, cannot easily move elsewhere (and certainly cannot move out of Scotland) then a local production tax seems particularly apt. Again, by setting it locally and by allowing local people a say in how it is set then they are in a position of power again and can directly benefit from our renowned exports.
Personally, I welcome the prospect of minimum unit pricing and do believe that it would be an effective aid to our national alcohol problem but my challenge to the government is that if the courts rule otherwise, there is still something we can do. Indeed, even if they don’t….why not both?
Next year brings in the Scottish Parliamentary Elections and with it comes the proposals from each of the parties on how best to use the limited powers that the Scottish Government will have at its disposal. No doubt, much of the news and comment will be around whether or not the (marginally) expanded powers over income tax coming in under the Scotland Bill 2012 will be used and by how much.
Our approach towards local taxation, however, will perhaps lead to a far more fundamental change to the fabric of our society. There is also far greater scope within the devolution powers to do something a bit more radical that simply raising or lowering the rate of tax by a penny or so (or repeatedly defending one’s reasons for not doing so). It is therefore important, before the campaigning season begins in earnest, to understand what our options are and the potential impacts of them.
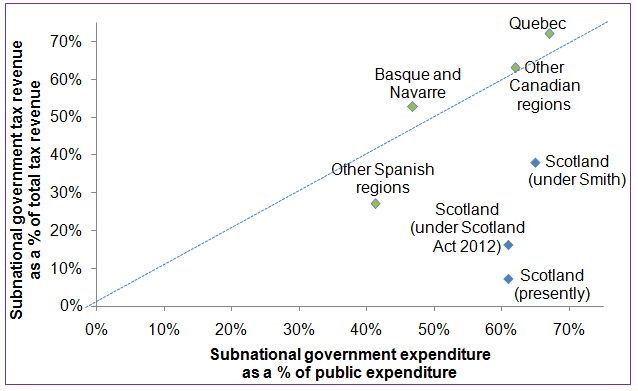
A comparison of the % of devolved control in Scotland now, as it will be under the Scotland Act 2012 and under Smith Commission recommendations as well as a comparison with Spain and Canada. Source: Scottish Government.
Monday the 9th of November saw the Scotland Bill 2015 make a further step towards completion. This Bill, which has been the result of the aftermath of the 2014 independence referendum, will mark another milestone on the devolution “journey” Scotland is traveling upon.
Some of the commentary both during the actual debate in the House of Commons and in the days since have shown considerable confusion at just how the system of devolution in the UK works at the moment and how it is to change with the implementation of the Bill. Before we really settle into a meaningful debate on whether or not any “additional powers” for Scotland will be to and for Scotland’s benefit we need to actually understand what those new powers are, what we have now and how they can be used.
This article shall focus on the powers over taxation devolved to the Scottish Parliament as this area will be undergoing several rapid changes over the next few years and much of the confusion amongst members of the public has arisen from the conflation of several phases of devolution.
One must understand the rather unplanned and piecemeal nature of the progression of devolution for Scotland, there is certainly no clear “destination” to that “journey”, and this reflects and contributes to the confusion but there are three major points in the form of the Scotland Act 1998 which formed the Scottish Parliament after the success of 1997 Devolution Referendum; the Scotland Act 2012 which resulted from the 2007 Calman Commission and the aforementioned Scotland Act 2015 resulting from the Smith Commission of 2014.
Last night George Osborne’s Fiscal Charter was voted on and rammed through Parliament on the back of the Tory’s majority. Today, the media focusing more on the shambles that is the current Labour party and their confused approach to supposed Opposition combined with the rumbling rebellion in the ranks as the party tries in vain to come to terms with what their members actually want the party to stand for.
Consequently, as usual, much less has been said about the actual contents of the Bill and its effects on our economy.
Q. When is a surplus not a surplus?
A. When someone is talking down the Scottish Government.
Today the Auditor General published its annual report detailing an independent opinion on how well the Scottish Government is managing its finances (or how badly it is failing to do so).
This year, as last, there have been howls of anguish from those opposed to the Scottish Government at the fact highlighted by the Auditor General that the Government spent £350 million less last year than it was given in the Block Grant.
As the opening question suggests in most normal countries when your government spends less than it has available to spend then it is running what is known as a budget surplus. This is, especially in today’s economic climate, generally considered to be a “good thing“. Not so in Scotland, apparently, where the phrase to be used instead is “budget underspend”.
How this has occurred, is due to the peculiar way by which the Scottish Government is funded and is constrained to spend its money.
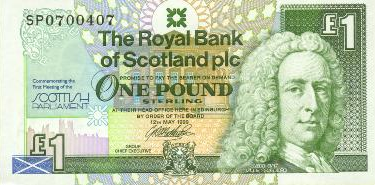
An RBS £1 Note – Scottish Parliament Commemorative Issue
It’s fairly widely acknowledged that one of the weaker aspects of the 2014 Scottish Independence debate was that surrounding currency. I still hold to my long-standing view that all options open to us were and are equally viable. All come with unique benefits, all carry characteristic risks. All that was required was the will to manage those risks. Scottish Independence should never have even been about the question “Which currency should we use?”. I believe that instead, the real question was “Should we, in Scotland, have the right to ask that question?”
Recently though, the catastrophic circumstances facing Greece have focused minds back to this first question and many are now convinced that before we go into another debate on independence we must be able to answer the questions we failed to answer last year. So let us take a scenario where Scotland is faced with setting up its own currency. Just what would that involve?